For Iowa borrowers who didn't fit the bank's checklist
Didn't fit the bank's checklist? That doesn't mean no.
Plenty of solid Iowa borrowers hear no because their situation doesn't fit a standard box: self-employed income, a recent job change, a rental property, or credit that isn't perfect. Mike has shopped multiple lenders for Iowa borrowers since 2005. Tell him what you're working with, and he lays out anything in your way before you ever apply. He does the lender shopping. You just tell him what's going on.
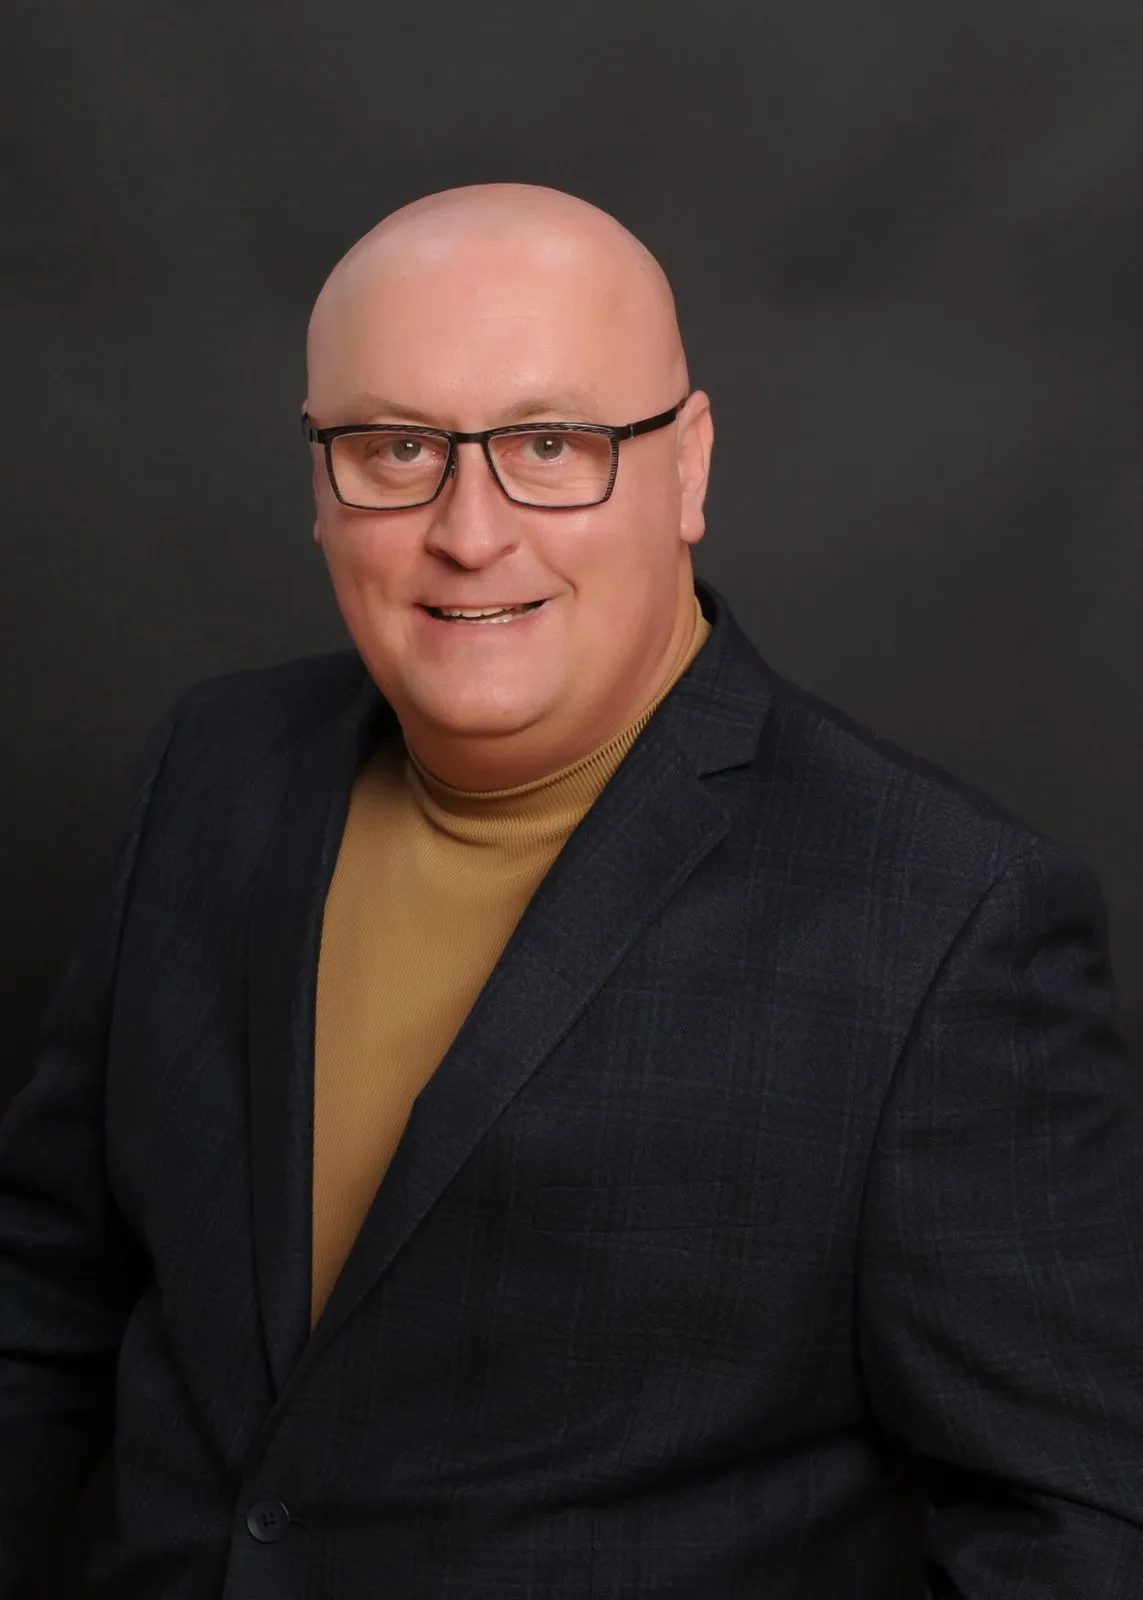
Mike Steger, owner of Iowa Mortgage Solutions.
You know exactly why they said no.
Maybe your income comes from your own business, and a bank couldn't make sense of it. Maybe you changed jobs recently and got told to come back in two years. Maybe it's a rental property, or credit that's fair but not perfect. You make decent money. You have savings. And you still walked away with a form letter instead of a real answer, or worse, felt judged for asking a basic question.
Coming up with the down payment is one problem. Being talked down to while you try is another one you shouldn't have to deal with.
Here's the thing: a bank has one checklist. Mike is a broker who has shopped multiple lenders for Iowa borrowers since 2005, so he sees different checklists, and he knows which obstacles are real before anything gets submitted.
One bank's checklist, or a broker who shops around?
| One bank | Mike, your broker | |
|---|---|---|
| Self-employed income | Read against one rigid formula | Read by lenders built for it |
| When you don't fit the box | Automatic no, form letter | A real person looks at why |
| Who tells you why | Often nobody, or a form letter | Mike, one-on-one |
| When you learn about obstacles | Often deep into underwriting | Before you ever apply |
| How many lenders see your file | One | Multiple, shopped for you |
What a second opinion actually includes
- ✓A one-on-one review of your situation with Mike
- ✓A plain list of anything standing in your way, before you apply
- ✓Your file shopped across multiple lenders, not just one
- ✓A credit decision goal of the same day or within 24 hours, once you apply
- ✓A message left gets a call back immediately or the next business day
- ✓No shame about credit, savings, or asking basic questions
Will this just end in another no?
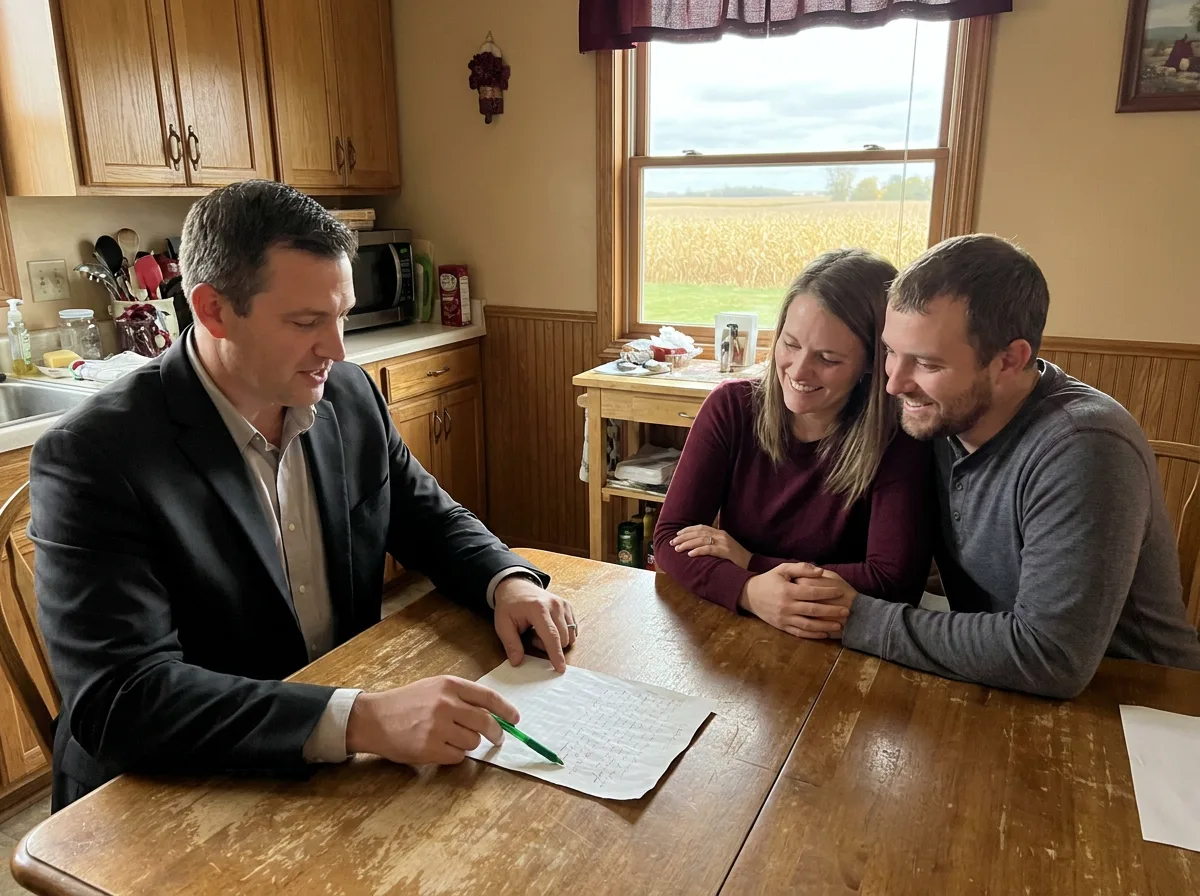
That's the real question. You already got turned down once, and a fresh application feels like another credit pull and another chance to be judged. Here's the difference: Mike lays out anything that could get in your way one-on-one, before you apply, not after. If credit is going to be an obstacle, he tells you that up front. Nobody promises approval, and that's the point: a straight answer includes the no parts too.
"What's the catch?"
None. Mike lays out anything that could get in the way before you apply, so nothing shows up as a surprise later.
Do I need perfect credit or a lot saved up?
No. Mike works with people in all kinds of credit situations. Questions about credit or savings are expected, and you won't be made to feel small for asking them.
What happens after you hit send
Tell Mike what you're working with
Two minutes, through this form.
A mortgage consultant calls you
Immediately, or the next business day.
One-on-one obstacle review
Mike lays out anything in your way, before you apply.
You decide, then apply
Credit decision goal: same day or within 24 hours.
What real clients say about Mike
"Fast, professional, and reliable service. They worked hard to get me the best rate possible and kept me updated every step of the way. Highly recommend!"
"Mike Steger is great!! He was very responsive and jumped in head first to help us! Definitely recommend Mike if you are looking to buy a home!"
"Mike Steger was great to work with all three times. This is the third loan my family has went through Iowa Mortgage Solutions... When Mike says let him make it happen he does just that."
"Amazing people to work with. ... Mike, Mike and Marcy were amazing and worked with us and always checked in with us and made sure everything was done. ... 1000% recommend!"
Know before you apply.
- Mike tells you up front if credit is going to be an obstacle, before you apply.
- One-on-one work to assess your situation and lay out any obstacles in your way.
- Credit decision goal: the same day or within 24 hours of your application.
- Leave a message and a mortgage consultant calls you immediately or the next business day.
This isn't a promise of approval. It's a promise that you know where you stand, before you ever apply, from someone who tells you the truth.
Is this for you?
This is for Iowa buyers and homeowners who:
- ✓Were turned down or stalled somewhere else
- ✓Are self-employed
- ✓Changed jobs recently
- ✓Own or want to buy a rental property
- ✓Just want a straight answer before applying again
It's not for:
- ✕Properties outside Iowa
- ✕Large commercial or multifamily investment deals
- ✕Rate shoppers with a big down payment who only want the lowest quoted rate
From Mike
I've been a mortgage broker in Cedar Rapids since 2005. I work with Iowa borrowers only, and I shop your file across multiple lenders instead of working from one bank's checklist.
I'd rather tell you about an obstacle now, before you apply, than let a deal blow up in underwriting after you've already gotten your hopes up. Self-employed income, a recent job change, a rental property, credit that isn't perfect: I've seen all of it, and I'm not going to make you feel small for any of it.
Tell me what you're working with, and I'll tell you straight whether it works.
A few quick questions
Does a prior denial disqualify me?
No. A no from one lender is one lender's answer. Tell Mike what happened and he'll look at your whole picture.
How is self-employed income looked at?
Mike works with lenders built to read self-employed income correctly, not just one rigid formula.
Do investment properties and cash-out refinances count?
Yes. Both are part of what Mike works on.
What does Iowa-only mean?
The property has to be in Iowa. Mike works with Iowa borrowers exclusively.
Will trying again hurt my credit or end in another denial?
Mike tells you up front if credit is going to be an obstacle, before you apply again.
What happens after I send the form?
A mortgage consultant calls you back immediately or the next business day.
Didn't fit the bank's checklist? That doesn't mean no.
Tell Mike what you're working with, self-employed income, a job change, a rental property, or credit that isn't perfect, and he'll tell you straight whether it works. Iowa homes only. No pressure, just a real answer.
Or call (319) 377-1988